
Credit Card Utilization Ratio: Why the 30% Rule Is Costing You FICO Points
You may have thought that having less than 30% on your credit cards will give you the best score. However, this isn’t actually true. In reality keeping it between 1%-6% can increase your score by 40+ points.
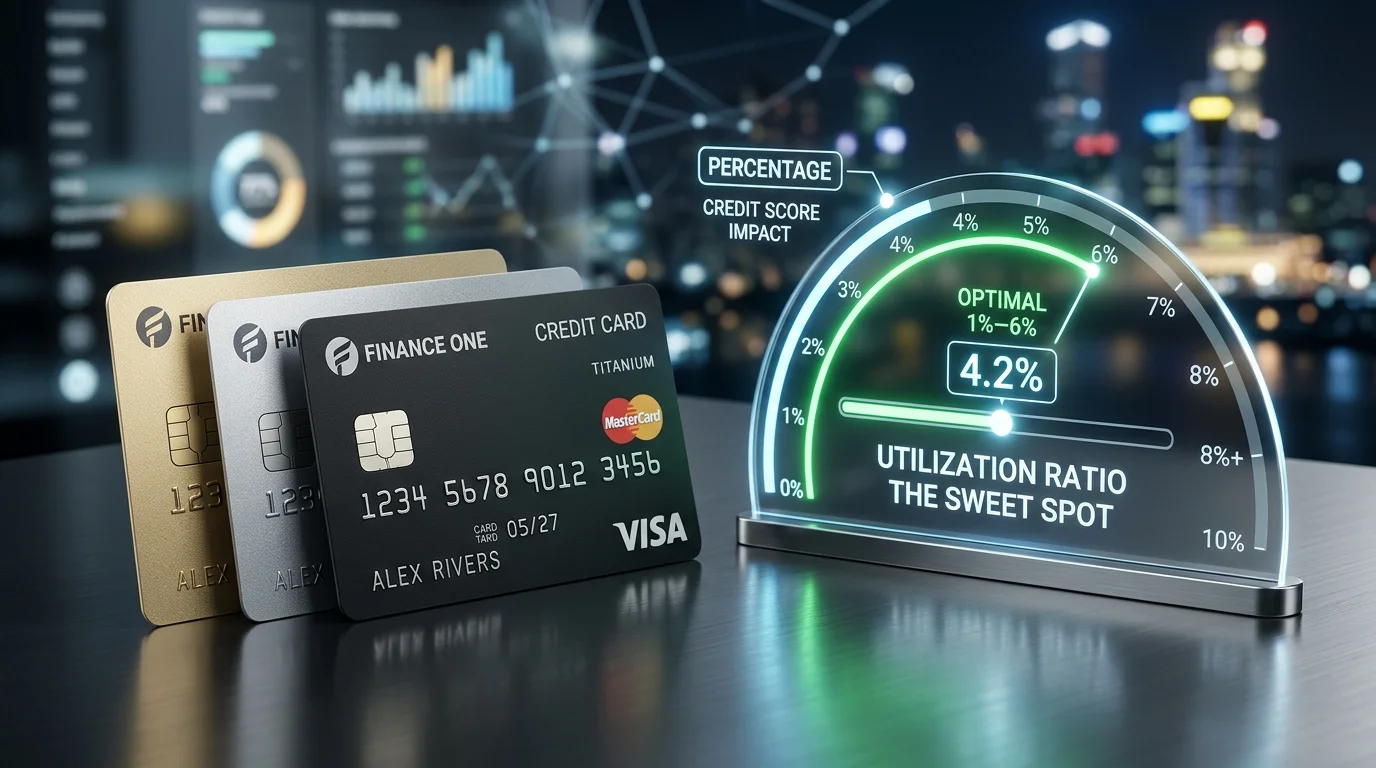
Table of Contents
You may have seen many posts online, or heard in many personal finance debt-related podcasts, that the best thing to do with your credit card balances is to never exceed 30% of your limit. Many people follow this advice and have a $2,800 balance on a $10,000 limit card, but are still left stuck in the 600s or low 700s for their FICO score. The 30% rule is not best practice and in fact, once your utilization exceeds 30%, you start to see large penalties.
Amounts Owed (mainly revolving utilization) makes up 30% of your credit score, second only to Payment History (35%). Once you understand how credit utilization is calculated by credit reference agencies, you can gain between 40 to 60 marks in just 30 days.
FICO scores are awarded based upon credit card utilization in different bands:
- Band 1 (1% – 6%): For an excellent score, aim to be in Band 1.
- Band 2 (7% – 19%): A good score is achieved in Band 2.
- Band 3 (20% – 29%): If you fall in Band 3, you may notice a drop in score.
- Band 4 (30%+): If you fall into Band 4, you may see large drops in score. In Band 4, you can expect to lose 30 to 70 points on average.
FICO Credit Card Utilization Bands Compared
Credit bureaus and scoring algorithms do not treat utilization linearly. As your balances cross into higher utilization tiers, scoring penalties accelerate rapidly. The table below outlines how FICO treats each utilization band:
| Utilization Band | Utilization Percentage | Credit Tier Rating | Estimated Score Impact |
|---|---|---|---|
| Band 1 | 1% to 6% | Excellent (Optimal) | Maximum scoring points awarded (+40 to +60 points vs. Band 3/4) |
| Band 2 | 7% to 19% | Good (Low Risk) | Minor point deduction (5 to 12 points below Band 1) |
| Band 3 | 20% to 29% | Fair (Moderate Risk) | Noticeable point drop (15 to 25 points suppressed) |
| Band 4 | 30% and higher | High Risk Warning | Severe penalty; average loss of 30 to 70 FICO points |
How To Improve Score using Statement and Due Dates
One of the biggest mistakes made with credit utilization is to confuse the Due Date with the Statement Date.
Statement Date
A monthly snapshot of balances are taken by the credit card company. This is what will be sent on your bill.
Impact on FICO score:
This means that this balance is reported to Experian, Equifax & TransUnion. This reported balance determines your utilization for the whole month.
Due Date
Between 21–25 days AFTER the Statement Date. If paid by this date, no interest will accumulate on your balance.
Impact on FICO score:
Paying by this date on credit cards has NO impact on credit utilization. It only impacts on-time payments.
If you charge $2,800 on a $3,000 credit card, and pay it in full on the due date, you will not get charged any interest. However, you will be reporting 93% utilization to the credit reference agencies. Aim to pay 95% of your charges 2–3 days before the Statement Date in order to improve your score.
Double Penalties: Card-Specific Utilization & Overall Utilization
There are two credit utilization calculations used by FICO:
- Total Utilization (Overall): Total balance owed on all cards divided by total credit limit.
- Individual Card Utilization: Balance owed on individual cards divided by individual credit limits.
Imagine having 2 credit cards:
- Card A: Credit limit of $20,000 and a balance of $0.
- Card B: Credit limit of $2,000 and a balance of $1,800.
Your overall credit utilization is $1,800 / $22,000 = 8.1% – great! But, because Card B has an individual utilization of 90% ($1,800 / $2,000), your score will be penalized by 30 to 45 points for having "high risk on a single revolving account." Try to keep all individual cards below 10%.
Boosting your Score Quickly for Mortgages/Autos
If you are looking to apply for a mortgage or car loan, and want to improve your score quickly (by 25 to 40 points) within 72 hours to get the best interest rates, ask your mortgage loan officer to do a “Rapid Rescore”:
- Bring all credit card balances below 5%: Pay down all revolving accounts until balances are at zero or under 5%.
- Get a confirmation letter or receipt: Obtain documentation from the credit card company to show that all balances are now $0 (or very low).
- Submit confirmation to underwriter: Submit the confirmation to your mortgage underwriter. They will pass on the confirmation directly to Equifax, Experian & TransUnion.
- Fast-track credit file update: The credit reference agencies will update your credit profile within 48 to 72 working hours (compared to 30 days for regular updates). This means you will get a higher score for your loan immediately.
With FICO 8, past utilization levels have no impact on your current score. So if you had 85% utilization in March (getting a score of 670) and reduce it to 2% in April, you will get a much better score in April, as if the high utilization never occurred.
Note: With newer FICO 10T & VantageScore 4.0, 24 months of trended data is considered, so keep utilization low regularly.
The AZEO Method Example (All Zero Except One)
The best way to improve credit scores is using the AZEO method. When all cards report $0, FICO penalizes your score by 12 to 20 points for inactivity. The AZEO method ensures active reporting while keeping utilization in Band 1:
- List All Credit Cards: Record the statement dates for all credit cards in a spreadsheet.
- Choose One Reporting Card: Choose one main credit card (ideally a major brand such as Visa/Mastercard and NOT store cards).
- Clear All Other Cards: On all other cards, pay them off completely. Pay 3 days before the statement date to ensure that a $0 balance is on the statement, and therefore reported to credit reference agencies.
- Leave a Small Balance on Reporting Card: Ensure that the Reporting Card shows a small balance of between $15 and $30 (less than 3% utilization).
- Pay Small Balance by Due Date: Pay the $15–$30 amount in full to avoid interest. Repeat the process every month.
Utilization & Authorized User Tradelines
If you become an authorised user on a credit card with a $25,000 limit and a $500 balance (2%), the full $25,000 limit will be included in your total utilization. This will immediately improve your utilization %. Within 30 to 45 days, your score should improve significantly as the tradeline is posted across all three bureaus.
Frequently Asked Questions
How often do credit card companies report balances?
Credit card companies generally report balances once per month. They will report either on the day, or within 2 working days of your Statement Date. If you make payments mid-month, this means that low utilization will be reported.
Will my utilization be low if I pay my credit card in full each month?
No, if you pay on the due date. If you have charged $4,000 to your $5,000 credit card, and it creates a statement, you will be reporting 80% utilization. Even if you pay in full on the due date (30 days AFTER), it will still show as 80% utilization. To avoid this, make an early payment before the statement closing date.
Can I increase my credit limit without a hard search?
Many major credit card companies (American Express, Capital One, Discover & Citi) will only make a soft check on your credit file if you increase your credit limit through their website/app. A soft check will have NO impact on your credit score. However, some credit card companies may make a hard search. If this is the case, consider whether the increase in credit score from reduced utilization will be worth it considering the 3–5 point drop caused by the hard search.
How does installment loan balance affect Amounts Owed?
Although revolving credit has the highest impact on your score, installment loans will also be considered. FICO will divide the remaining balance of the loan by the original loan amount to calculate utilization. If you reduce your car/student loan to less than 9% of the original loan amount, you will gain an additional 10 to 18 marks on most credit scores.
Accelerate repayment of balances and calculate interest savings with our free Credit Card Payoff Calculator.
Financial Disclaimer: This article is published for educational and informational purposes only and does not constitute personalized financial, legal, or investment advice. Always consult with a licensed fiduciary financial advisor before making significant financial commitments.
Editorial Standards: Our writers and editors uphold strict standards of editorial independence. Advertising or partner compensation does not influence our research, ratings, or advice.
Editorial Team
Managing Editor & Site AdministratorThe MoneyWise editorial team is dedicated to producing actionable, unbiased, and mathematically sound personal finance guidance for US consumers.
Related Articles
View all
Debt Avalanche vs Debt Snowball: Which is Best?
Oct 22, 2026 • 7 min read
Best High-Yield Savings Accounts Guide
Oct 5, 2026 • 9 min read
Best Starter Credit Cards for Building Credit
Oct 4, 2026 • 9 min read
How to Freeze Your Credit for Free Across All 3 Bureaus
Oct 3, 2026 • 9 min readGet Practical Money Tips in Your Inbox
Join our newsletter and receive the latest articles, tips and tools straight to your email.
Build a Stronger Financial Future
Explore our free calculators and resources to make smarter money decisions.
Try Free Calculators