
Sinking Funds 101: Never Get Caught Out By Expected Costs
Car repair, christmas presents and yearly insurance isn’t an emergency. Learn how to master sinking funds so that you never go over your monthly budget.
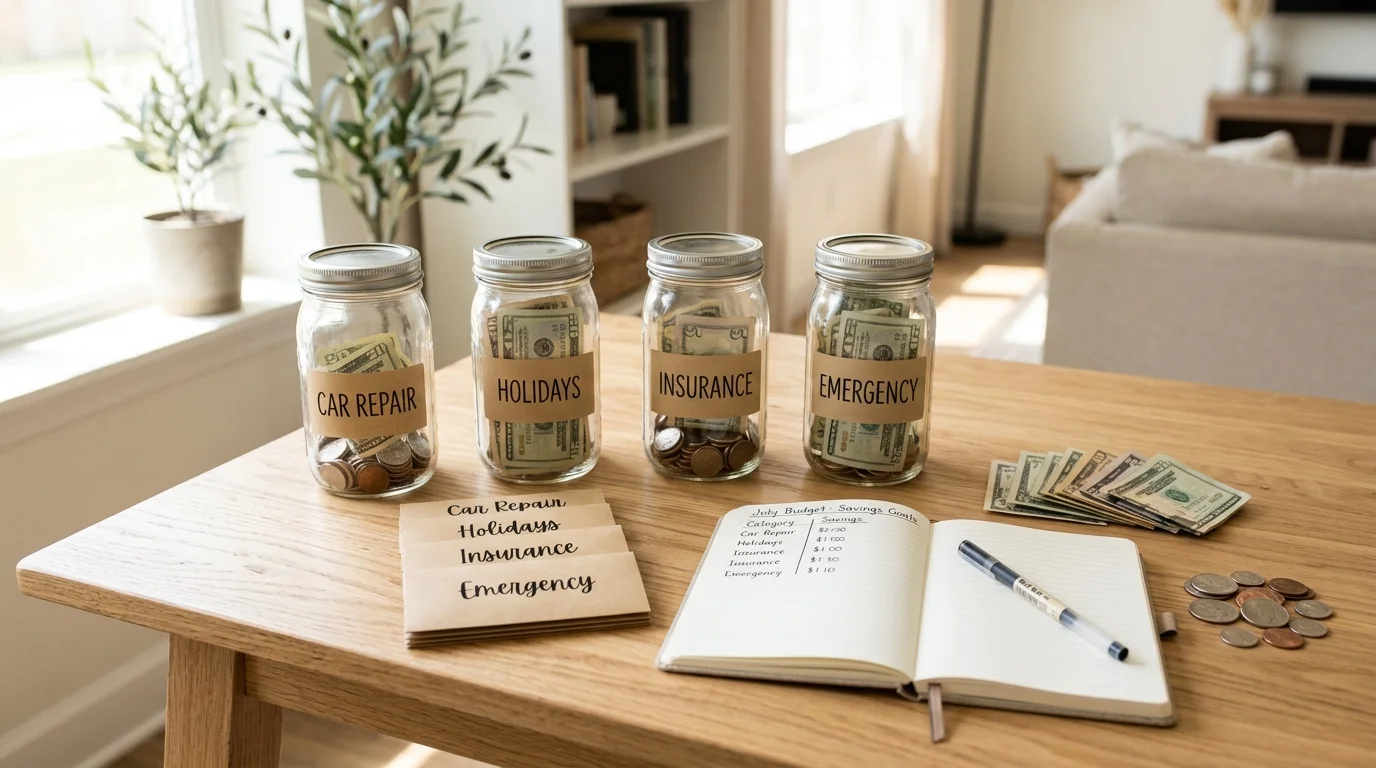
Table of Contents
Every December, millions of consumers go into a frenzy of panic about how they’re going to afford holiday gifts. Every 6 months there’s a cash-flow issue when drivers receive their semi-annual car insurance payment and every Spring when house owners get their local property tax bill. However these are all 100% predictable and unavoidable recurring costs.
If you’re not accounting for this kind of irregular bills then you’ll be left in a pickle. Taking money out of your emergency cash or putting it onto a high-interest credit card. To stop the never-ending cycle of stress and maths you need to learn how to utilise sinking funds.
A sinking fund is a type of savings account that you put a small amount of money into every month for a specific and predictable future expense.
Sinking Fund vs Emergency Fund
The main reason why people’s households go into budget melt-down is because they’re confusing situations of disaster with irregular costs. Over a third of adults will borrow money when hit with sudden costs of multiple hundreds of dollars. Here’s a table to help:
| Feature | Emergency Fund | Sinking Fund | Regular Savings |
|---|---|---|---|
| Purpose | Provides protection from disaster. | Helps pay for predictable, recurring or planned costs. | General savings for future goals. |
| Predictable | Unpredictable. | Very predictable. | No set time to spend. |
| Examples | Losing a job, unexpected surgery, large flood in house. | New tyres, vet visits, Christmas gifts, holidays. | Saving for house deposit or general financial freedom. |
| Emotion | Creates high levels of stress. | 100% guilt free to spend. | Neutral. |
| Goal | 3-6 months of your basic living costs. | Exact amount of money you need to pay for the cost. | Varies depending on your long term net worth goals. |
When you use your emergency fund to pay for new brake pads on your car you feel defeated. You’ve used some of your safety net. However if you have an allocated Auto Maintenance Sinking Fund you’ll feel in full control. You were saving for that exact invoice!
Sinking Fund Calculation
You don’t need to do any complicated spreadsheets or maths. You just need to know 3 things:
Monthly Contribution = Total Cost ÷ Months Until Cost
Let’s say you have an annual car insurance policy that costs you $1,200 in November. You want to save in January so you have 11 months to save:
$1,200 ÷ 11 months = $109.09
This means if you automate $109 per month into your insurance sinking fund you’ll turn that scary 4 figure bill into a regular monthly cost.
The 6 Must Have Sinking Funds
While you can create sinking funds for almost any lifestyle goal here are the 6 must have ones to avoid almost 90% of recurrent budget issues.
1. Auto Maintenance & Registrations
Even the most reliable cars will need oil changes, brake pads, tyre rotations and licence plate renewals. Consumer reports show that the average driver spends around $1,000 per car per year on regular maintenance. Saving $80-$100 per car per month will avoid you falling into high interest credit card debt.
2. Pet Costs & Vet Visits
Regular vet visits, rabies vaccinations, flea/heartworm prevention and grooming can all be predicted. Saving $50-$75 per pet per month will ensure your animal friend gets the loving care they deserve without impacting your household budget.
3. Holidays
According to the National Retail Federation (NRF) the average consumer spends around $900 on winter gifts, postage, meals and decorations. Opening a holiday fund in January and saving $75 will mean you have 100% cash funded holidays.
4. Home Maintenance & Appliances
As a rule of thumb in financial planning you should save 1% of your property value per year. This means if your home is worth $350,000 you should save around $3,500 per year or $290 per month. This will help with plumbing, water heater and HVAC maintenance.
5. Medical Costs & Deductibles
Even the best health insurance will have deductible, co-payments, dental and prescriptions. Saving $100-$150 per month into a medical sinking fund or maxing out your triple tax advantage Health Savings Account (HSA) will help protect your day to day checking account.
6. Travel, Holidays & Milestones
Vacations should be a relaxing time! Don’t let them become 12 months of high interest revolving credit card debt. Putting $250 per month into a holiday fund will allow you to spend $3,000 on a memorable summer holiday with no worries.
Don’t get carried away creating 25 micro funds for small things such as haircuts, streaming and eating out. Keep these within your general variable budget. Stick to 4-6 major sinking funds to keep your banking simple.
Where Should I Put My Sinking Funds?
Never keep your sinking fund money in your checking account. If you have excess money in your debit card you’ll start to get lifestyle creep and start spending your car insurance fund on eating out and shopping online. Instead try one of these 2 options:
- High Yield Savings Accounts (HYSA) with Multiple Buckets: Many modern banking apps such as Ally, Capital One 360 or Marcus by Goldman Sachs allow you to create multiple buckets within one account. This means your money is FDIC protected, earning you a healthy 4-5% APY and keeping your money in different buckets.
- Multiple Savings Accounts: If your bank doesn’t offer buckets you can easily create multiple savings accounts. Label them as Auto Care, Travel or Annual Bills.
Use our free Monthly Budget Calculator to calculate your total monthly fixed and variable costs.
How to Start Using Sinking Funds
- Budget Audit: Have a look through your debit and credit card statements from the last 12 months. Highlight any irregular costs that caused you stress.
- Order by Date: Order them by date. If your property tax is due in 90 days make sure you prioritise that. This means you’ll be putting money into that bucket first.
- Automate: Set up a recurring payment to go through the exact morning your pay comes in. This makes budgeting super easy.
If you don’t have your emergency net yet read our full guide on How to Build a 6 Month Emergency Fund Fast.
Frequently Asked Questions
How many sinking funds should beginners have?
Beginners should only have 3 essential sinking funds: Car Maintenance, Annual Irregular Costs (Insurance/Property Tax) and Christmas Gifts. After you’ve been consistently saving for 90 days with no over drafts you can add Travel/Home Maintenance/Wedding funds.
Should I Start Sinking Funds while paying off high-interest credit cards?
Yes! Whilst using our Debt Snowball Calculator to pay off your credit cards. Create small bare bones sinking funds for essential costs such as car repairs. If you don’t save $50 per month for car repairs you’ll be stuck using your credit card again as soon as you have a flat tire.
What if I don’t use all my money in my sinking funds?
Any excess money will stay in that bucket so you’ll be saving less per month next year. Or you can celebrate and add the excess to your emergency fund or Roth IRA.
Can I invest my sinking funds?
No! Never invest your sinking funds in index funds, stocks or anything volatile if you have less than 3-5 years until you need it. If the market drops 15% temporarily and you need money for your car insurance/property tax you’ll be losing out. Always keep your short term funds safe in a High Yield Savings Account.
Financial Disclaimer: This article is published for educational and informational purposes only and does not constitute personalized financial, legal, or investment advice. Always consult with a licensed fiduciary financial advisor before making significant financial commitments.
Editorial Standards: Our writers and editors uphold strict standards of editorial independence. Advertising or partner compensation does not influence our research, ratings, or advice.
Editorial Team
Managing Editor & Site AdministratorThe MoneyWise editorial team is dedicated to producing actionable, unbiased, and mathematically sound personal finance guidance for US consumers.
Related Articles
View all
How to Save $5,000 in 6 Months: The Exact Bi-Weekly Paycheck Blueprint
Nov 20, 2026 • 5 min read
50/30/20 vs. 70/20/10 vs. 60/20/20: Which Budget Percentage Rule Actually Works?
Nov 20, 2026 • 5 min read
The Automated Money Funnel: How to Save $10,000 in One Year
Nov 17, 2026 • 5 min read
The 30-Day No-Spend Challenge: Rules, Tips & Survival Guide
Nov 17, 2026 • 5 min readGet Practical Money Tips in Your Inbox
Join our newsletter and receive the latest articles, tips and tools straight to your email.
Build a Stronger Financial Future
Explore our free calculators and resources to make smarter money decisions.
Try Free Calculators